October 2, 2026
Cash Advance Apps That Work With Chime (2026): Verified List
Chime's own SpotMe and MyPay fees and limits, plus which cash advance apps confirm Chime support on their own help pages.
Read article
Is Money App cash advance legit? Yes, provided you mean the specific app publishing under that name: Money App - Cash Advance, built by PRG Ventures, Inc., a subsidiary of PROG Holdings, Inc, which trades on the New York Stock Exchange under the ticker PRG. That distinction matters because "Money App" is a generic enough name that a search for it could just as easily turn up MoneyLion, Dave, Empower, or an unrelated app using a similar label, and none of those are the product this review covers.
I pulled the listing straight from the Apple App Store and Google Play, checked the parent company's own site, and fetched the live BBB profile before writing a word of this review. Where the app's own marketing copy lines up with those primary sources, I'll say so plainly, and where a claim can't be independently confirmed, I'll flag exactly that instead of smoothing it over.
The app in question is published by PRG Ventures, Inc., listed as the developer on both the Apple App Store listing and the Google Play listing under the package name com.prgventures.moneyapp. PRG Ventures is a subsidiary of PROG Holdings, Inc., the fintech holding company that trades on the New York Stock Exchange under the ticker PRG and also owns Progressive Leasing. PROG Holdings describes the product in its own words: "MoneyApp is a simple, digital cash-advance app that helps people cover everyday expenses when they need extra flexibility between paychecks," and calls it part of "PROG Holdings' broader mission to expand access to practical, inclusive financial solutions."
A publicly traded parent company doesn't guarantee a flawless product. It does mean there's a real business behind the app, one that files with the Securities and Exchange Commission (SEC) and answers to shareholders rather than an anonymous developer account you can't trace back to anyone. The Better Business Bureau profile lists the business as based in Draper, Utah, with an operating history dating back to August 12, 2021.
The same BBB profile shows Money App is not BBB accredited. Non-accreditation alone isn't a red flag: plenty of legitimate companies skip the voluntary accreditation process because it costs money and doesn't change how the business actually operates day to day. The profile does tell you the letter grade BBB assigned the business and how many complaints customers have filed against it, which is a more useful signal of how the company handles disputes when a customer pushes back.
Money App's own App Store description rules out several categories by name. It states plainly: "Money App is NOT a personal loan, payday loan, cash loan, or an app to borrow money." The app positions itself as an earned wage access product, sometimes shortened to EWA: a tool that advances money you've already earned from work you've already done, ahead of your actual payday, rather than lending you money you haven't earned yet.
This framing is the app's own legal position, not a settled ruling from a court or regulator. Whether EWA products should be treated like loans, complete with the disclosures and rate caps that come with lending, is a live argument among regulators and consumer advocates right now.
I'm not going to pretend that debate is resolved here, because it isn't. What I can tell you is exactly what Money App charges today, which is the part you can verify for yourself before you sign up.
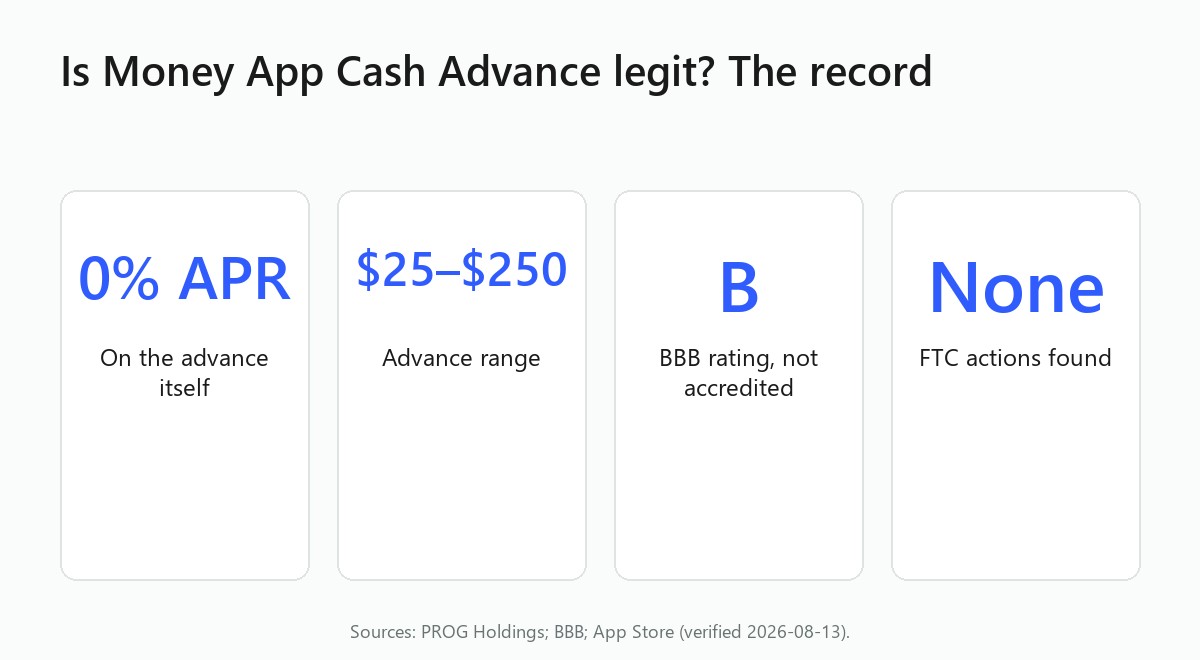
Money App's stated cost model, per its Apple App Store listing, is 0% annual percentage rate (APR) with no mandatory fees, no interest, no late fees, no mandatory tipping, and no monthly subscription. If that holds up in practice, a standard advance genuinely costs nothing beyond what you borrow. The one place money changes hands is optional: choosing expedited delivery instead of waiting for a standard transfer.
Standard delivery is free and takes one to three business days. Getting the same money into your account within minutes instead carries an optional express fee that scales with how much you're advancing, so a smaller advance costs less to expedite than a larger one. LendEDU's review of the app describes that express fee as a flat-ish per-transfer charge that generally falls somewhere in the mid-single to high-teens dollar range depending on advance size. Money App's own site returned an error when I tried to confirm the exact tiers directly, so treat that figure as a third party's characterization, not a number Money App has published where I could check it myself.
This fee structure only shows up if you choose speed over price. If your schedule allows the standard one to three business days, Money App's advance costs $0 beyond what you borrow, which is worth remembering since we've compared other cash advance apps with no monthly fee that follow the same pattern of charging only for speed, never for access.
Money App's advance range runs from $25 to $250 per advance, according to its Apple App Store listing. That's a narrower ceiling than some competitors that advertise much higher limits, and there's a catch worth flagging up front: new users don't start anywhere near the top of that range.
The app raises your limit over time as you build a repayment history, so your first advance is likely to land closer to the $25 floor than the $250 ceiling. Money App's own listing frames this as normal for new users, and it means the headline number in an app store listing isn't necessarily the number available to you on day one. If you need close to $250 immediately, this app probably isn't going to get you there on the first request, so plan around the floor of that range instead of the ceiling.
Standard delivery takes one to three business days and costs nothing; instant or express delivery is available for the optional fee described above and lands in your account within minutes rather than days, per the same App Store listing. If rent is due Friday morning, express delivery is the option on this app that gets you there in time. If you can plan even two or three days ahead, standard delivery does the same job for free.
Say you need $100 by Friday and it's already Wednesday afternoon. Standard delivery, initiated Wednesday, could plausibly land by Friday but cuts it close given the one to three business day window, while express delivery removes that uncertainty entirely for the price of the optional fee. Express delivery isn't a bad deal on its own. The real lesson is timing: the free option only pays off if you're not already up against the deadline.
Before Money App will advance you anything, it needs a linked checking account with a consistent direct-deposit history, and it does not run a credit check, per the same App Store listing. This direct-deposit requirement is how the app verifies you actually have earned income coming in, which is the entire premise behind calling this an advance instead of a loan.
Linking your bank account also means handing over more than your balance. Per Apple's App Store privacy disclosure for this app, Money App collects identity data (including your Social Security number for identity verification), bank account information, financial records, contact details, and payment information. It describes that data as protected with "bank-level encryption."
I can't confirm which specific vendor handles the bank-linking and verification step; the app's own site wasn't reachable when I tried to check, and neither store listing names the technology behind it. Handing an app your Social Security number and bank credentials is a meaningful decision regardless of which vendor sits behind the scenes, so it pays to know what to check before you trust any cash advance app with account access.
Money App holds a B rating from the Better Business Bureau, is not BBB accredited, and has 18 complaints on file as of August 13, 2026, with no government actions listed on its profile. Eighteen complaints against a company operating since August 2021 isn't an alarming number by itself, but the complaints themselves tell you more than the count does.
One reviewer on the BBB profile put it bluntly: "Takes all your information and then says they cannot verify your identity." This specific complaint lines up with a pattern reported separately by Finder and LendEDU: identity verification failures during signup, users losing eligibility for advances after building a clean repayment history, and difficulty reaching a human being for customer support instead of a chatbot (Finder specifically names the chatbot-only complaint). App-store review summaries echo those same themes. I'm treating all of this as directional rather than statistical, since it comes from a handful of secondary sources, not one large verified dataset.
On star ratings, Money App sits consistently in the mid-4s out of 5 on the Apple App Store and in the low 4s on Google Play, based on the current listings. Review counts on third-party aggregators vary too widely between sources to cite a single number responsibly, so I'm not handing you a fake-precise figure here.
For the regulatory side, I checked Federal Trade Commission (FTC) press releases and enforcement actions as of August 13, 2026, and found none naming PRG Ventures, Money App, or PROG Holdings specifically. This is a meaningful, verified absence, and it's worth stating plainly rather than implying a problem the record doesn't show. It also bears noting that an absence of enforcement action isn't the same as a clean bill of health; it just means no formal case has been filed against this specific company as of the date I checked, which is a narrower claim than "safe" and I want to be precise about the difference.
Money App fits someone who needs a small amount, in the $25 to $250 range, who already has consistent direct deposit and doesn't need the cash that same day. For that reader, waiting the standard one to three days is a genuinely fair deal for closing a short gap between paychecks.
It's a weaker fit if you need more than $250 immediately, since new users start well below that ceiling at first. It's also a weaker fit if you're not comfortable sharing your Social Security number and full bank access with a company whose bank-linking vendor isn't publicly named. The same goes if you live in a state Money App doesn't currently support; availability isn't confirmed the same everywhere, so check during signup instead of assuming coverage. And if reaching a real person for support matters to you, the recurring complaints about chatbot-only service are worth weighing first.
If the identity-verification friction or the chatbot-only support gives you pause, compare Money App against the wider field before you hand over your bank details. Our guide on how to choose a cash advance app in 2026 breaks down the criteria that actually separate one app from another: advance limits, how clearly express fees are disclosed, funding speed, and how a company handles support and disputes when something goes wrong.
For a straightforward, needs-based amount with no drama, Money App's pay-nothing-if-you-wait model competes fine against the rest of the field. If you'd rather never see a fee at all, even for speed, some apps in that same comparison price express delivery differently, so it's worth a direct look before deciding which one gets your bank details.
Yes. Money App - Cash Advance is published by PRG Ventures, Inc., a subsidiary of PROG Holdings, Inc. (NYSE: PRG), a publicly traded fintech company. You can confirm the publisher on the Apple App Store and Google Play listings, and the parent-company relationship on PROG Holdings' own site.
According to its own App Store listing, Money App charges 0% APR with no mandatory interest, late fees, or monthly subscription. The only optional cost is an express fee if you choose instant delivery instead of the free one to three business day standard transfer.
Advances range from $25 to $250, per the app's Apple App Store listing. New users typically start well below the $250 ceiling and see the cap rise as they build a repayment history with the app, so plan for an amount closer to the $25 floor on your first request.
Money App holds a B rating from the Better Business Bureau, is not BBB accredited, and has 18 complaints on file as of August 13, 2026, with no government actions listed on its profile. Plenty of legitimate companies skip the voluntary BBB accreditation process, and the business has been operating since August 2021, per its BBB profile.
No. A search of FTC press releases and enforcement actions as of August 13, 2026, found no action naming PRG Ventures, Money App, or PROG Holdings specifically. That absence doesn't guarantee future scrutiny, but there's no public enforcement record against this company right now.
Chime's own SpotMe and MyPay fees and limits, plus which cash advance apps confirm Chime support on their own help pages.
Read article
Gerald advertises zero fees, but a store purchase unlocks the transfer. Limits, speed, eligibility, and who it actually suits.
Read article
Comparing apps like Tilt cash advance? See how Earnin, Dave, Brigit, and MoneyLion stack up on fees, limits, and speed.
Read articleSee how the top earned wage access apps stack up on fees, limits, and speed. View the full ranking